 APPS
APPS


APPS

Apple Inc. just delivered its first earnings call since new Chief Executive John Ternus took over the company from Tim Cook on Sept. 1, and the results beat expectations on the top and bottom lines. But the company missed expectations on iPhone sales and offered disappointing guidance going forward, and the stock fell in late trading.
The company reported fourth-quarter earnings before certain costs such as stock compensation of $2.10 per share, comfortably ahead of Wall Street’s target of $1.99 per share. Revenue for the period rose 12%, to $114.48 billion, easing past the $113.39 billion analyst forecast. All told, its net income came to $30.71 billion at the end of the quarter, up from just $27.46 billion one year earlier.
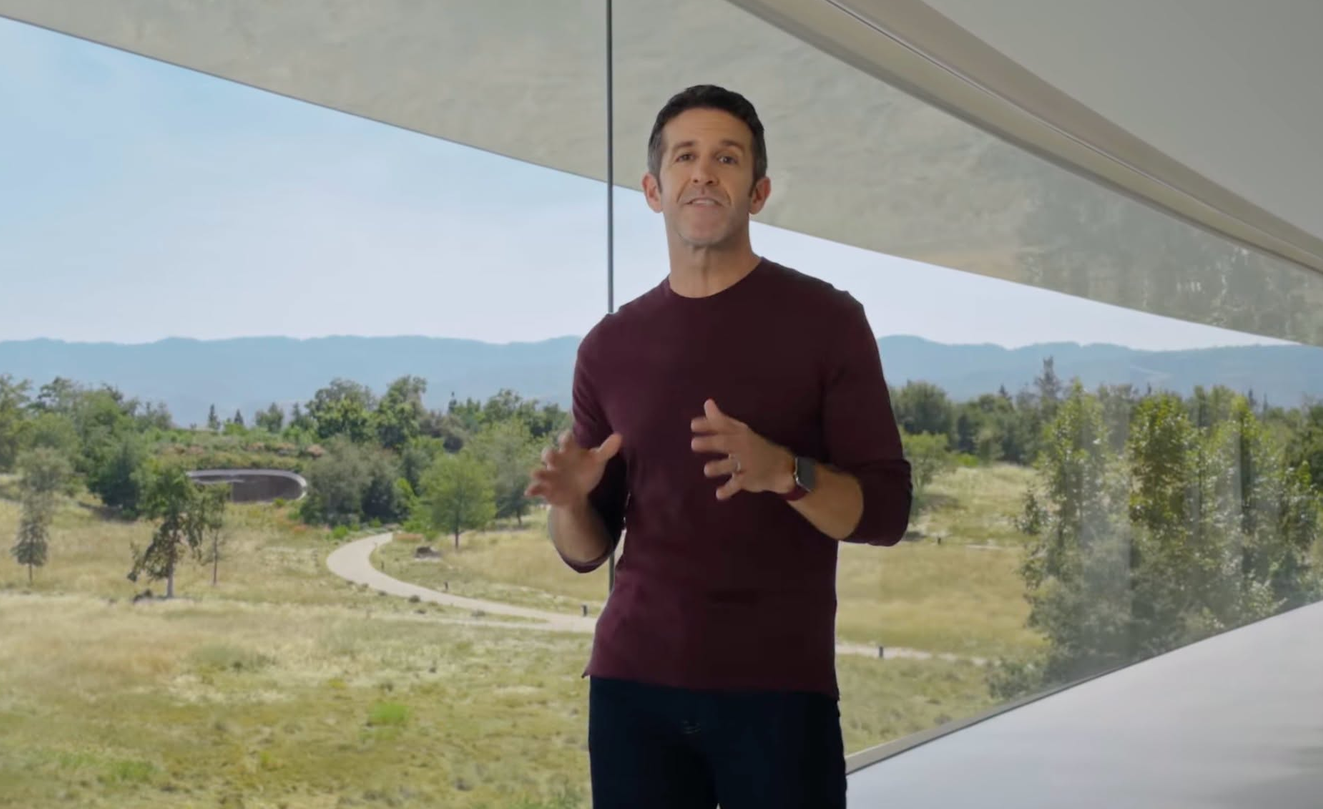
When Ternus (pictured) stepped up to relieve Cook in the CEO’s chair a couple of months ago, he realized he was stepping into a job with sky-high expectations, following in the footsteps of two of the most successful company leaders in American history. Steve Jobs was credited with revolutionizing consumer devices, while Cook took the company to spectacular new heights thanks to his operational expertise, establishing it as one of the world’s most iconic brands.
The weight of expectations is reflected by Apple’s enormous valuation. According to Oppenheimer analyst Martin Yang, the iPhone maker is trading at about 36 times next year’s expected earnings. That represents a premium compared with the rest of the technology market, even though its earnings are only expected to grow 1% this year, slower than many of its peers.
Nonetheless, investors have piled into Apple because it’s something of an outlier in the artificial intelligence boom. While its rivals are all spending hundreds of billions of dollars on building data centers, Apple has remained extremely capital-efficient, pouring cash into share buybacks and dividends for shareholders. That has given the company a strong margin for safety, but its position could still be threatened if Ternus can’t find a way to speed up Apple’s innovation engine.
The company has already been criticized for its lackluster performance in AI. Its long-awaited Siri AI chatbot finally arrived during the past quarter, but it came across as stale the moment it arrived. By the time it had launched, it had already been surpassed by autonomous AI agents such as Dots and Muse that can perform multistep tasks on behalf of users, while Siri is still fumbling around with answering questions.
Analysts wanted to know if Apple is planning to offer more AI features through subscriptions or services, but Ternus declined to reveal what the company’s future plans are. But he insisted that Apple has “lots of opportunities” for monetization in future. “One example is the hardware side, right?” he said. “It offers a compelling reason for upgrading or switching.”
The pressure is on for Apple to give consumers more reasons to buy its expensive devices, especially as the costs of those products have been getting higher. Today’s report was the first full quarter of higher-priced Apple products following a price hike in June that stemmed from the rising cost of memory supplies and other components.
The price of most iPhone handsets was hiked by around $100, but consumers didn’t appear to punish Apple. On the contrary, iPhone revenue was a bright spot, reaching $57.58 billion in the quarter, up 17% from a year earlier and above the $56.54 billion consensus estimate. That’s despite the quarter including only eight days of new iPhone 18 Pro sales and none of the new flagship device, the iPhone Duo.
Apple needed a good quarter from the iPhone because its main growth engine, the services business, is slowing. Revenue there came to $31.57 billion, just below the Street’s forecast of $31.58 billion, growing less than 10% during the quarter, its slowest rate of growth since September 2022. The business includes revenue from a wide range of products and services, such as iCloud storage, AppleCare warranties, App Store fees and licensing revenue from Google LLC for putting its search engine as the default option in the Safari browser.
“We saw strong performance in many service categories, with all-time records in video, cloud services, payment services and advertising, and a September quarter record in music,” Tetanus told analysts.
Apple saw a better performance in its Mac computer division, with sales of $10.79 billion comfortably topping the Street’s forecast of $9.61 billion. The unit’s revenue grew almost 24% on an annual basis, following the launch of new Mac Studio and Mac Mini laptops in August.
The iPad division was a disaster, however, as sales declined more than 10% from the previous year to $6.3 billion, trailing the Street’s forecast of $6.7 billion. Last month saw the launch of a new iPad Mini model, following the debut of the updated iPad Air back in March, but despite those releases, there has been no flagship model launching this year, and that appears to have hurt the business’ performance. When asked about the miss, Ternus blamed supply constraints and a difficult comparison with last year as the main reasons for its disappointing performance.
The disappointing performance of Apple’s services and iPad units was compounded by what was seen as weak guidance for the current quarter, which includes the peak Christmas sales period. Apple Chief Financial Officer Kevan Parekh didn’t offer concrete numbers, but said the company expects its revenue to grow by between 7% and 10% in the quarter. Wall Street analysts are looking for higher growth of 11.4%, however. Parekh also revealed that Apple is forecasting its gross margin to fall between 45% and 46%, declining from the fourth quarter.
Apple’s stock fell almost 3% on today’s report, but it’s still up more than 24% in the year to date compared with a gain of just over 10% for the broader S&P 500 index.
Support our mission to keep content open and free by engaging with theCUBE community. Join theCUBE’s Alumni Trust Network, where technology leaders connect, share intelligence and create opportunities.
Founded by tech visionaries John Furrier and Dave Vellante, SiliconANGLE Media has built a dynamic ecosystem of industry-leading digital media brands that reach 15+ million elite tech professionals. Our new proprietary theCUBE AI Video Cloud is breaking ground in audience interaction, leveraging theCUBEai.com neural network to help technology companies make data-driven decisions and stay at the forefront of industry conversations.