 BLOCKCHAIN

BLOCKCHAIN

A convergence of traditional financial institutions, blockchain innovators and a friendlier regulatory climate is carrying the world of decentralized finance into a new phase.
Earlier this month, the Securities and Exchange Commission debuted a five-year exemption for the trading of tokenized equities, digital tokens that represent a stock and can be traded on the blockchain. The announcement opened the door to a host of market-altering scenarios, including investor self-custody, fractional ownership of shares and 24/7 trading that could be settled instantly.
The SEC action provided further evidence that the world of passive payments is shifting to a model of intelligent capital movement, driven by the intersection of stablecoins, tokenized real-world assets and agentic artificial intelligence, all under the aegis of decentralized finance, or DeFi.
“These pillars are going to combine,” said Joseph Chalom, former BlackRock executive and currently the chief executive of the digital currency company Sharplink Inc. “We need to prepare for the new paradigm that’s coming.”
Chalom spoke during a panel discussion last week as part of the 10th Annual Fintech Conference hosted by the Federal Reserve Bank of Philadelphia. A key topic on the minds of finance industry executives and regulators was the future role of stablecoins and tokenized assets in the emerging era of programmable money.
Stablecoins are digital assets pegged to fiat currency, typically the U.S. dollar. They are designed to enable low-volatility and safe transactions in the crypto ecosystem.
The digital currency received a major boost last year with passage of the Guiding and Establishing National Innovation for U.S. Stablecoins or GENIUS Act, which standardized stablecoin rules across issuers and focused on reserve transparency and interoperability. However, when Congress attempted to set reserve requirements, audit standards and registration routes for stablecoins as part of the Clarity for Payment Stablecoins Act earlier this month, the bill failed passage in the U.S. Senate.
“This is a step backwards for our industry,” Ji Hun Kim, chief executive of the Crypto Council for Innovation, said during the Federal Reserve conference. “There’s going to be a lot more work in regulatory agencies to fill the gap.”
Despite the perceived setback for stablecoins, some leaders in the DeFi industry offered a different perspective, driven by the belief that a safer route for programmable money involved tokenized assets. While stablecoins can be issued by nonbanks with federal or state charters, tokenized deposits are digital representations of actual commercial bank money backed by FDIC insurance.
“I don’t see stablecoins as a future for retail payments,” Greg Baer, president and CEO of the Bank Policy Institute, said during one panel session. “The obvious alternative is tokenized deposits.”
An example of the ways that fledgling DeFi companies are seeking to bridge traditional finance, or TradFi, with tokenized systems is Custodia, a special-purpose depository formed to serve as a compliant link between the U.S. dollar payments system and digital assets. In June, Custodia unveiled a bank-architected token sub-ledger called Hazel Network, designed to safely bridge traditional banking with tokenized systems.
Hazel Network creates a frictionless, programmatic path for stablecoins to come back to the originating bank as tokenized deposits, thereby reducing fears that dollar stablecoins, with no bank account behind them, could drain traditional financial institution reserves.
“Tokenized deposits are going to eat stablecoins’ lunch,” Caitlin Long, founder and CEO of Custodia Bank, said during a panel session last week.
While the financial world sorts out the impact of stablecoins vs. tokenized deposits, it must also deal with the growing influence of AI. This month saw the U.S. debut of Muse, a personal AI agent designed by Meta Platforms Inc., which can make purchases for a user via a new kind of payment infrastructure built by Stripe Inc.
The AI agent topped 730,000 downloads within five days, and surpassed OpenAI Group PBC’s chatbot as the most popular free app on the App Store. Finance executives are mindful that agents such as Muse could have a significant impact on their industry.
“Muse is taking something incredibly detailed, such as agents, and making it stupidly simple,” said Robert Bench, co-founder and CEO of Radius Inc. “They are going to tilt the space.”
How AI agents affect the financial world will be shaped by their dual role as a payments enabler and shopper. In August, the enterprise payments infrastructure provider Rain Inc. announced the launch of the Agentic Payments Alliance, a coalition of 26 founding members that included Visa and Mastercard. Rain facilitates agentic payments through its Agent Control Layer that was unveiled in June.
Agents running on Rain’s platform currently execute travel bookings, software subscriptions, end-to-end procurement workflows and cross-border money transfers. “There’s emerging greenspace here,” said Rain CEO Farooq Malik.
The broader implications of agentic AI as a shopper are still to be determined within the finance industry, but markets are already reacting. The launch of Meta Muse triggered a selloff in banking stocks this month, as investors reacted to fears that agentic AI could change the levers of shopping power.
“You will be able to tell your agent to maximize your yield,” said the Bank Policy Institute’s Baer. “It will challenge the banking industry.”
One factor that could slow the effect of AI on certain sectors of the financial industry is that building effective shopping agents is not an easy task. Last week, online retail giant Amazon.com Inc. signaled its interest with the introduction of a new agentic artificial intelligence service for third-party sellers on its main e-commerce site. Amazon also booted Muse off its platform, expressing concerns over customer security and user experience.
“Shopping is much more difficult, it’s a much more subjective determination,” said Brendan Woodbury, senior manager of payments policy at Amazon. “It’s harder to do a shopping agent well.”
There is also a growing debate over accountability for AI agents, whether that involves payments or shopping. Last week, a group of banks, including Bank of America and Capital One, issued a warning that agents for online shopping could increase the risk of scams, fraud and data privacy breaches affecting consumers.
“You have to answer the question for every transaction of who’s accountable,” said Sebastian Gunningham, CEO of money transfer platform provider Remitly Global Inc. “When you give that over to agents, that’s going to be a super-interesting question to answer.”
A subtext running through the dialogue at the Federal Reserve conference in Philadelphia this week was the friction between the TradFi world and the burgeoning DeFi community.
Questions around the role of stablecoins and their place in the global payment ecosystem persist. A study by Flagship Advisory Partners earlier this year found that only 5% of U.S. adults own stablecoins and merchant acceptance of the digital currency hovered around 6%.
“I see ourselves twisting into a pretzel to explain to someone in Argentina whether this is a dollar or not,” Gunningham said. “Is the stablecoin what they want? That bridge has to be crossed.”
There are also issues around the ability of existing financial infrastructure to support a new paradigm for decentralized finance and autonomous decision-makers. Traditional banking rails pause payment settlements on national holidays and over weekends, yet Rain has claimed to be the first fintech company to settle Visa card transactions seven days a week.
“We need to be talking about the future of plumbing,” said Sharplink’s Chalom. “The current rails don’t support it.”
Despite significant progress in gaining regulatory approval for cryptocurrency transactions, some industry figures remain concerned that the premise of a digital financial system for empowering people to lend, borrow, trade and earn interest without banks or middlemen is being lost in the shuffle. This month’s Congressional rejection of the Clarity Act may have been the best thing for the cryptocurrency world, according to Jai Massari, co-founder and chief legal officer of Lightspark Inc. and a lecturer at the Stanford Law School.
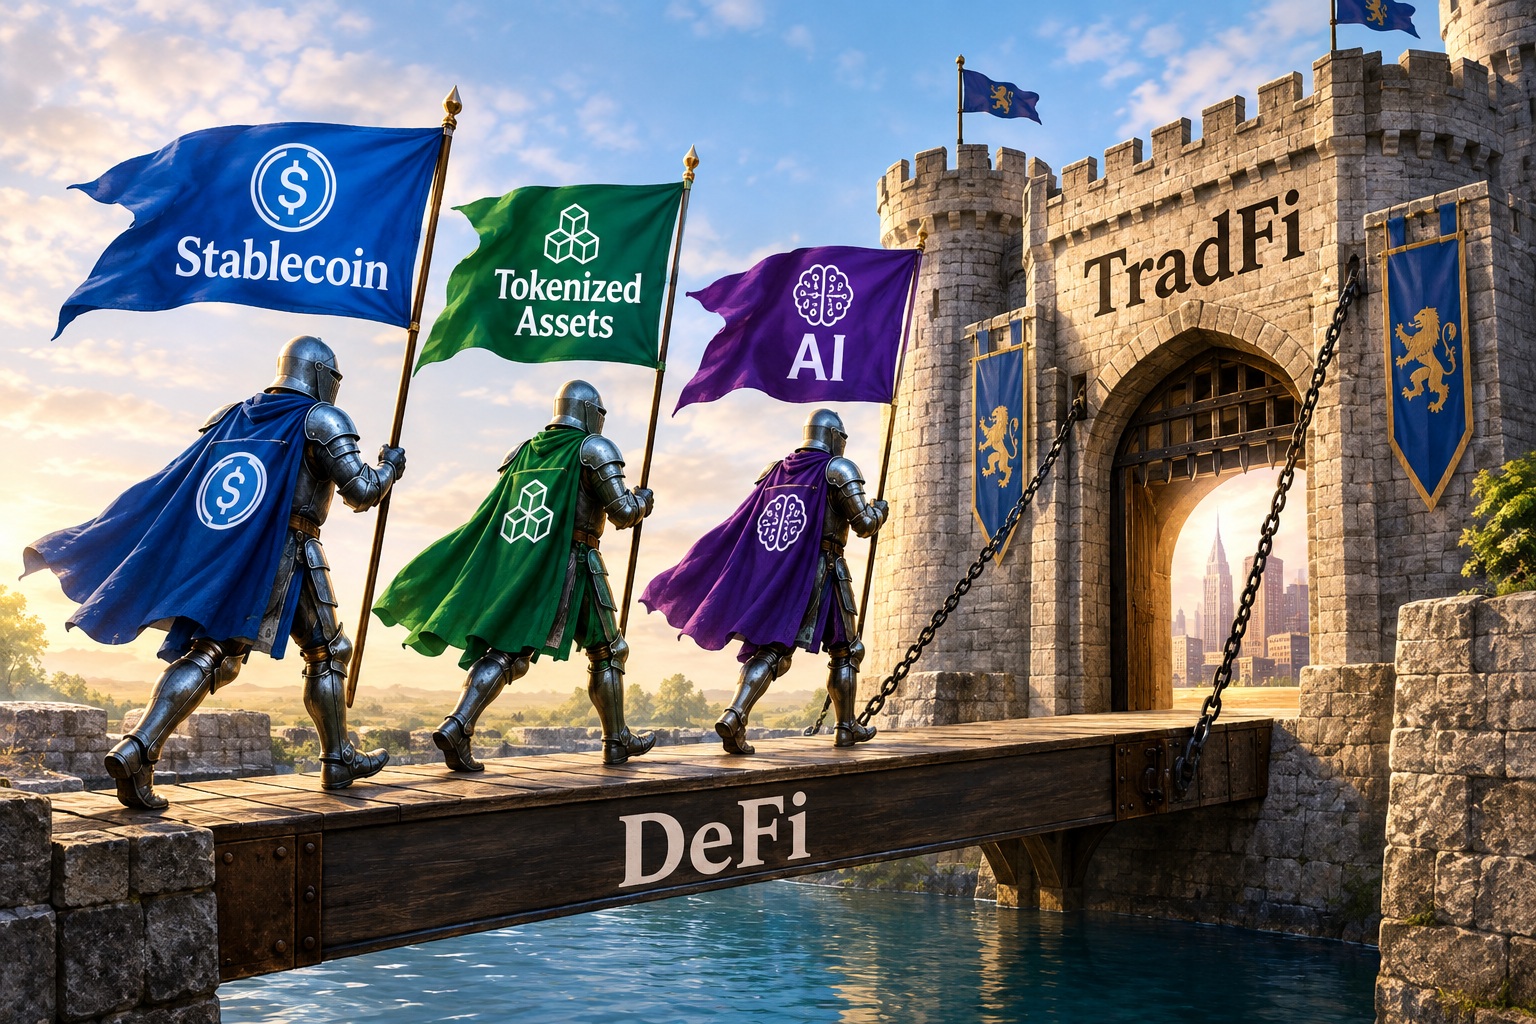
“Clarity was lowering the drawbridge so traditional finance would storm the crypto castle,” Massari said. “The crypto industry is not done yet and they have something meaningful to build.”
Support our mission to keep content open and free by engaging with theCUBE community. Join theCUBE’s Alumni Trust Network, where technology leaders connect, share intelligence and create opportunities.
Founded by tech visionaries John Furrier and Dave Vellante, SiliconANGLE Media has built a dynamic ecosystem of industry-leading digital media brands that reach 15+ million elite tech professionals. Our new proprietary theCUBE AI Video Cloud is breaking ground in audience interaction, leveraging theCUBEai.com neural network to help technology companies make data-driven decisions and stay at the forefront of industry conversations.