 INFRA
INFRA


INFRA

Chipmakers Qualcomm Inc., Arm Holdings Ltd. and GlobalFoundries Ltd. struggled to move the needle today after reporting financial results that clearly left investors wanting more.
After an impressive earnings beat from Advanced Micro Devices Inc. just 24 hours earlier, investors may have had heightened expectations, but if they did, they were clearly let down by the shaky performance of Qualcomm, which beat expectations on earnings but missed on revenue and offered weak guidance. The result was predictable, with its stock down more than 6% after-hours.
Both Arm and GlobalFoundries did better, but it wasn’t enough to satisfy investors who are becoming increasingly concerned about the sustainability of the artificial intelligence industry that has driven significant growth for all three chipmakers over the last couple of years.
The biggest disappointment was Qualcomm, which reported fourth-quarter earnings before certain costs such as stock compensation of $2.17 per share on revenue of $10.44 billion, up just 8% from a year earlier. The results were mixed, with Wall Street looking for earnings of $2.16 per share on sales of $10.48 billion. For the current quarter, Qualcomm said it’s looking for earnings of around $2.25 per share at the midpoint of its guidance range on sales of $10.48 billion, falling short of the Street’s target of $2.27 per share in earnings and $10.48 billion in revenue.
Qualcomm’s troubles stem from the fact that it has less exposure to the AI industry’s rampant growth than many other chipmakers. The bulk of its sales comes from system-on-chips and modems for smartphones, but the market is currently reeling due to the rising cost of components such as memory, which have forced handset makers to bump up their prices, reducing demand. Qualcomm has tried to weather the storm by raising the prices of its own chips recently, but its smartphone chip sales fell 26% in the quarter to just $5.14 billion, well behind the Street’s target of $5.21 billion.
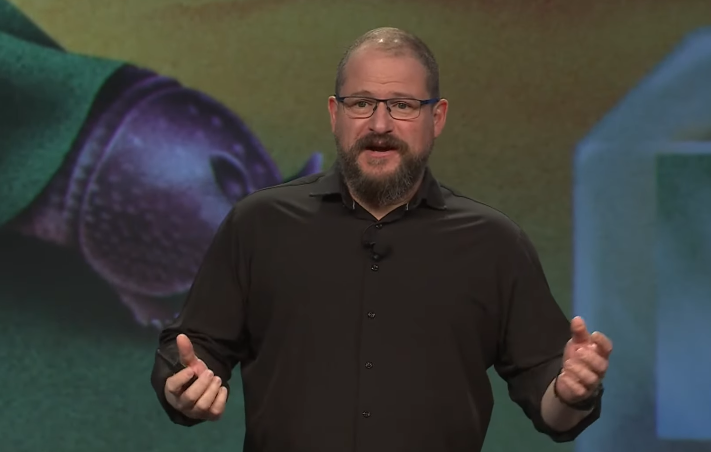
Under its Chief Executive Cristiano Amon (pictured), Qualcomm has tried to pivot and grow its position in alternative chip markets, particularly the AI data center industry. Revenue from that segment rose to $650 million during the quarter, but it’s still dwarfed by the smartphone business. Nonetheless, Amon insisted that the company will grow its data center business to more than $5 billion in revenue by the end of fiscal 2027. He said the company recently struck a deal with an unnamed global hyperscaler for optical connectivity chips. “We don’t have a demand issue; it’s a supply issue,” he told analysts on a conference call. “If I had more supply, I would probably be doing better.
Qualcomm’s automotive business was a bright spot, with sales there rising 89% to $1.99 billion in the quarter, above the Street’s consensus estimate of $1.66 billion. Internet of Things revenue came to $1.88 billion, up 4% from a year ago and just ahead of the Street’s estimate.
Finally, there’s Qualcomm’s QTL business, which generates revenue from licensing intellectual property for modems, 5G connectivity and other technologies. That segment added $1.3 billion in revenue, down 7%, despite signing renewed licensing agreements with Apple Inc., Transsion Inc. and Huawei Technologies Co. Ltd.
Chip design company Arm delivered much more palatable results, but it was somewhat cautious with its guidance for the current quarter, with the result being that its stock was down 2% in late trading today. The company reported adjusted earnings of 52 cents per share, just beating the Street’s target of 48 cents, while revenue rose 27% from a year earlier to $1.44 billion, ahead of the $1.38 billion analyst estimate.
Unlike Qualcomm, Arm doesn’t manufacture complete chips for its customers, but instead designs and licenses processor blueprints for customers such as Apple Inc., Samsung Electronics Co. Ltd. and Qualcomm to build their own custom chips. Where Arm is more similar to Qualcomm is in its strategy, where it too is also pivoting to focus on data center chip designs, trying to tap into the demand for AI compute. Arm said its data center business was the main growth driver this year, with royalties there doubling year-over-year.
However, Arm’s guidance did little to excite investors. The company said it’s looking for earnings of 56 cents per share, plus or minus four cents, compared to Wall Street’s forecast of 55 cents per share. For revenue, it’s targeting $1.54 billion, plus or minus $50 million, which is just ahead of the Street’s $1.52 billion target.
GlobalFoundries did a little better than its peers today, posting results and guidance for the current that squeaked past expectations. However, its stock remained flat after-hours.
The company reported third-quarter adjusted earnings of 53 cents per share on sales of $1.9 billion, up 12% from a year earlier, with growth driven by strong demand from AI and data center customers, it said. The results were better than expected, with analysts targeting earnings of 51 cents on revenue of $1.89 billion.
GlobalFoundries’ also differs from Qualcomm, in that it’s a pure-play contract manufacturer that builds the processors designed by semiconductors firms, rather than designing chips itself or selling them under its own brand. Qualcomm is actually one of its biggest customers, alongside Broadcom Inc., NXP Semiconductors N.V. and Infineon Technologies Inc. As such, its fortunes are very much aligned with those of the chip designers it caters too.
For the current quarter, GlobalFoundries said it’s looking for earnings of 59 cents per share, plus or minus five cents, on revenue of around $2 billion. Wall Street is looking for earnings of 57 cents per share and has the same revenue target.
Support our mission to keep content open and free by engaging with theCUBE community. Join theCUBE’s Alumni Trust Network, where technology leaders connect, share intelligence and create opportunities.
Founded by tech visionaries John Furrier and Dave Vellante, SiliconANGLE Media has built a dynamic ecosystem of industry-leading digital media brands that reach 15+ million elite tech professionals. Our new proprietary theCUBE AI Video Cloud is breaking ground in audience interaction, leveraging theCUBEai.com neural network to help technology companies make data-driven decisions and stay at the forefront of industry conversations.